Most students hear the word “stocks” long before they encounter “asset class,” so the rest of investing can seem closed off or needlessly technical. If you are studying or starting your career, that vocabulary gap can make it difficult to tell what a portfolio contains and why its pieces may react differently.
Learning the broader framework is not about chasing returns or finding a supposedly perfect investment. It is about understanding why portfolios combine assets that behave differently, then seeing which forms of ownership a small budget can realistically reach. The distinction becomes especially important when familiar labels hide different costs, access rules, and selling constraints.
The Main Asset Classes Every Investor Should Know
A portfolio can look varied while still depending on a single source of risk. An S&P 500 index fund and another broad stock fund hold different securities, but both can fall when investors retreat from public equities. Understanding different types of investments beyond stocks begins with recognizing that variety alone does not create portfolio diversification.
The simplest map has four main asset classes: equities, fixed income, cash and cash equivalents, and real assets, plus a fifth catch-all category for alternative investments. Lists describing six or seven categories simply separate alternatives into real estate, commodities, private markets, cryptocurrency, and collectibles.
Stocks, bonds, and cash are traditional investments, while everything outside that trio is generally treated as alternative. Modern Portfolio Theory explains why the mix matters more than one selection. Useful diversification comes from assets responding differently to the same event, ideally through low correlation to public markets.
Bonds Are the Usual First Step Beyond Stocks
A bond is a loan from an investor to a government, municipality, or company. Instead of representing ownership, as a stock does, it generally pays scheduled interest and returns principal at maturity. That structure helps fixed-income securities behave differently from equity.
Government bonds and Treasuries have the lowest default risk within this group because the national government backs them. Corporate bonds offer higher interest to compensate for company-specific credit risk. Municipal bonds, issued by state and local authorities, typically exchange some yield for tax treatment that can benefit eligible investors.
Interest-rate risk follows one memorable rule: when newly issued bonds pay more interest, older bonds with lower coupons become less valuable to buyers. Selling before maturity can therefore produce a gain or loss even when the issuer continues making every payment.
Beginners usually encounter bonds through target-date funds, bond funds, or bond ETFs rather than individual issues. Funds divide money across many bonds, while individual bonds often trade in denominations too large for a small account. Savings bonds offer another accessible route, although they do not trade like fund shares.
Tangible Assets: Property, Commodities, and Metals
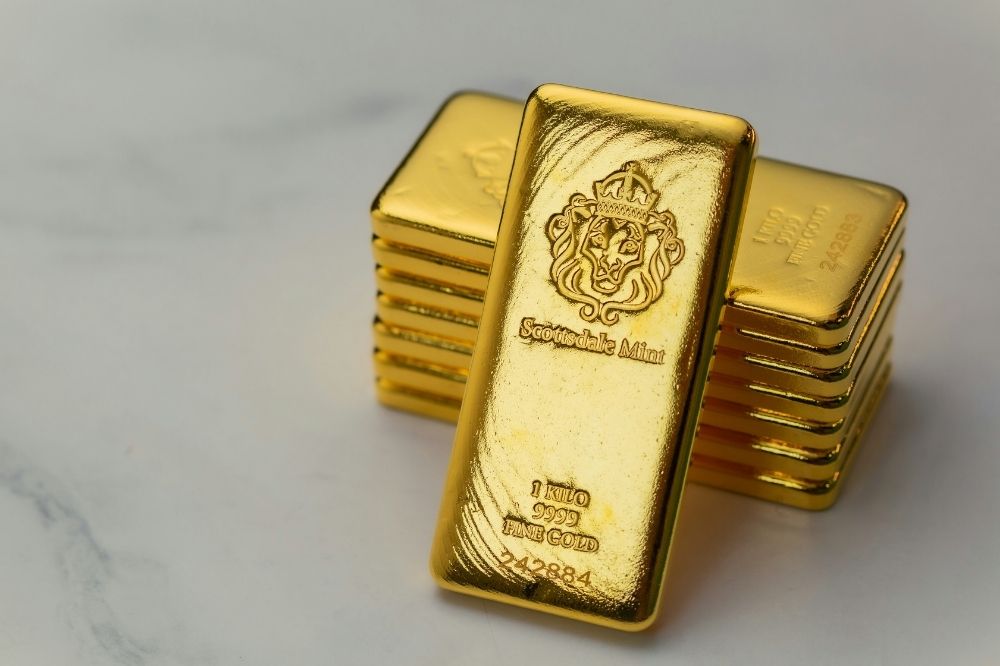
Real assets derive value from property, materials, or scarce objects rather than solely from a company’s earnings. Their pricing drivers can create low correlation to public markets, but ownership also brings storage costs, specialist pricing, and slower sales.
Real Estate Without Buying a Building
Direct real estate means owning a building, arranging financing, collecting rent, maintaining the property, and accepting a landlord’s responsibilities. It requires more money and involvement than purchasing a security.
A REIT holds income-producing property, and its shares can trade on an exchange much like stocks. REIT ETFs spread exposure across multiple property owners and sectors instead of relying on one building. Crowdfunding platforms pool money into individual developments or property portfolios, but these deals often have multi-year holding periods. Unlike a listed REIT, an investor usually cannot sell whenever the market is open.
Physical Metals Versus Paper Gold Exposure
Precious metals create three exposures that sound similar but work differently. Bullion coins and bars provide direct ownership, gold ETFs seek to follow the metal’s price, and mining stocks represent equity in operating companies. A miner’s costs, management, and production can move its share price independently of gold.
Physical ownership adds a dealer premium above the spot price, authentication concerns, secure storage, insurance, and a bid-ask spread when selling. Listings of gold eagles for sale, including those available through Monex, show how premiums differ among sellers and coin sizes, whereas an ETF bundles access into a traded share. Recognized sovereign coins, such as American Gold Eagles, are common retail formats, but recognition does not remove those ownership costs.
Commodities, Crypto, and Collectibles
Commodities include materials such as oil, wheat, and copper. Since storing barrels or bulk crops is impractical for ordinary investors, exposure usually comes through futures-based funds. Those funds hold contracts rather than the goods, so their performance can differ from changes in the current cash price.
Cryptocurrency works differently. Bitcoin trades continuously and has no corporate earnings to compare with its price. Collectibles and fine art have an even less visible valuation process. They lack live market quotes, and their value becomes observable only when a buyer bids. Condition, authenticity, provenance, transaction costs, and a limited buyer pool affect what the owner can receive.
What a Student Budget Can Actually Reach
The practical dividing line is not whether an investment sounds sophisticated. Some categories are accessible with a modest account, while private funds and direct property remain unavailable to most students. Access depends on purchase size, account rules, fees, and the ability to sell.
Low-Minimum Routes: ETFs, Fractional Shares, REITs
Fractional shares allow a brokerage to divide one full share into smaller interests. If a share costs more than the amount available, the investor can purchase a fraction rather than letting the share price dictate the entire allocation.
Broad ETFs place hundreds of holdings inside one tradable security. Bond ETFs apply the structure to fixed income, while REIT ETFs provide exposure to multiple property companies. These funds do not eliminate market risk, but they reduce dependence on one issuer or building.
Physical metals also scale down, though less neatly. Fractional-ounce coins require less cash than full-ounce versions, yet smaller coins often carry higher premiums relative to their metal content. The entry cost remains the coin’s value plus that premium, not the large subscription commonly associated with a private fund.
Accredited Investor Rules, Fees, and Lock-Ups
Private equity, private credit, and hedge funds generally restrict participation under U.S. Securities and Exchange Commission (SEC) accredited investor rules. Accreditation rests on income, net worth, or certain professional qualifications, not on investment knowledge.
Cost creates another divide. Index ETFs commonly charge a small annual percentage of assets. Many alternative investments combine higher minimum commitments with management fees and, in some structures, performance fees. Those layers reduce what remains for the investor.
Illiquidity is often the less obvious barrier. A lock-up makes committed money contractually unavailable for a stated period, potentially lasting years. With thin trading, an art owner or private-deal participant might be allowed to sell but wait months for a buyer offering a reasonable price. Money needed for tuition next semester does not belong in either structure.
Building a Mix That Suits Your Timeline
Each asset class performs a different job, so the useful question is not which one is universally best. Instead, it is which assets match the investor’s timeline, tolerance for price changes, and ability to leave money inaccessible.
Beginner portfolios commonly keep broad, liquid holdings at the core and use smaller satellite positions for less familiar assets. That structure supports portfolio diversification without allowing one mistake, storage expense, or difficult sale to dominate the account.
The deadline for the money remains the deciding factor. Funds needed soon require accessibility and price stability, while a longer timeline offers more room for assets that fluctuate or take time to sell.
